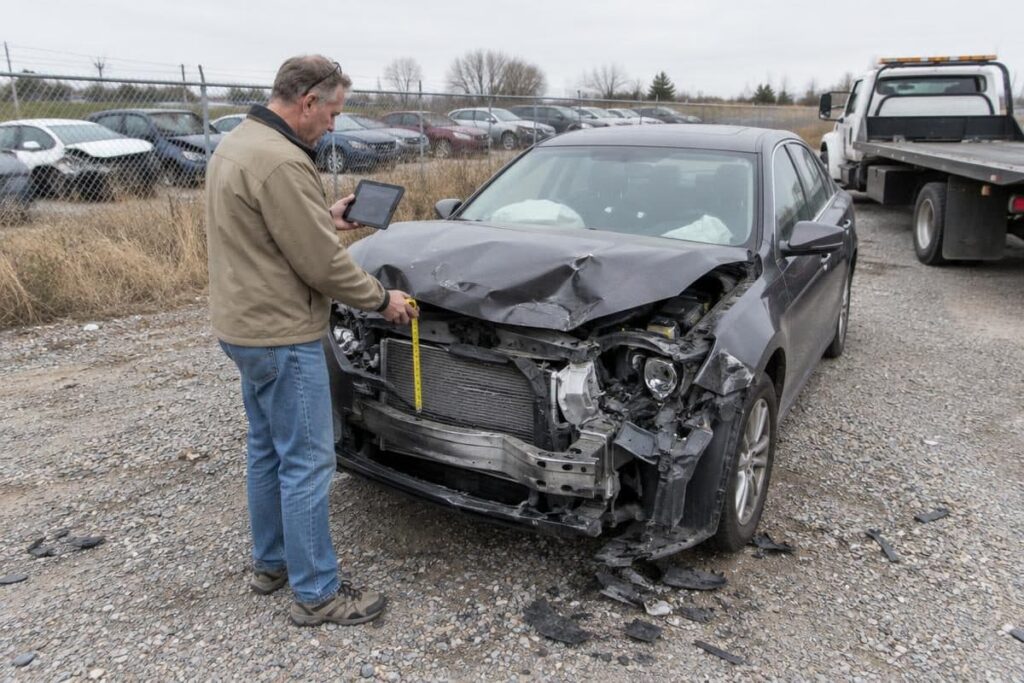
Is it better to have a car totaled or repaired? It depends on three numbers you can check yourself: the car’s actual cash value (ACV, what it was worth the minute before the crash), the repair estimate, and what the wreck would fetch as salvage. Where you live then decides where the line sits. In 30 jurisdictions that line is a percentage of value, from 65 percent in Nevada to 100 percent in Texas and Colorado. The other 21 rely on the total loss formula. Run your claim through the tool below, then read why a car written off under the legal line can still keep a clean title.
Enter your state, the ACV from the claim letter or a pricing guide, the shop’s estimate and your collision deductible. Salvage value is optional; leave it blank and the tool assumes 25 percent of value. You get the local rule with its citation, the damage ratio, the formula check, the settlement if the car is written off, the cash you would get by keeping it, and what each outcome does to the title.
Totaled or Repaired Calculator
Pick your state and enter what the car was worth before the crash and what the repair estimate says. You get your state's rule, whether the insurer is likely to write the car off, the claim check either way, and what keeping the car on a salvage title pays.
Your Claim Outlook
Estimates only, not a quote or legal advice. Thresholds come from two published compilations checked against statute text in eight states, with Rhode Island and Oklahoma updated for 2026; the District of Columbia figure is unverified. Your policy, the adjuster's valuation and supplements decide the real outcome. Reviewed October 2026.
The legal line is a title rule, not the insurer’s limit
Most of the percentages in the table below decide when a title must be branded salvage. They do not stop an insurer from declaring a total loss sooner, and once the insurer declares one, the claim pays value instead of repairs. The claims law firm Matthiesen, Wickert & Lehrer puts it bluntly in its 50-state chart: carriers can declare a total loss at any level of damage, and a car written off at 75 percent where the line is 80 percent can go to auction with a clean title.
So the useful question is not “did I cross the line?” but “does the insurer’s math say total?” Insurance companies compare the cost of repairing the car plus its salvage value against the value of the car. When that sum meets or beats ACV, writing a check is cheaper for them than paying a repair shop, and a supplement for hidden damage only pushes it further.
Rhode Island is the exception that runs the other way. Its 2026 law, which took effect June 26, makes 85 percent an insurer rule: below it, the owner chooses whether the car is declared a total loss.
Total loss threshold by state (51 jurisdictions)
Thresholds vary by state, and two of them moved in 2026. When we checked the published tables in October 2026, the most widely copied one still listed Rhode Island at 75 percent and Oklahoma at 60. Rhode Island went to 80 percent in 2025 and 85 percent this year. Oklahoma’s SB 1920 raises its line to 70 percent for losses on or after November 1, 2026.
TLF means no percentage is set in law and the formula below applies. Rows come from the Matthiesen, Wickert & Lehrer chart and a July 2026 insurance-industry table, which agree on every row; we checked eight against statute text, including Florida 319.30, Iowa, Nevada, Texas, Wisconsin and New York. The District of Columbia figure has a single source and is marked unverified.
| State | Rule | Authority |
|---|---|---|
| Alabama | 75% | Ala. Code 32-8-87(d) |
| Alaska | TLF | Alaska Admin. Code tit. 2, 92.170 |
| Arizona | TLF | A.R.S. 28-2091 |
| Arkansas | 70% | Ark. Code 27-14-2301 |
| California | TLF | Cal. Veh. Code 544, 11515 |
| Colorado | 100% | C.R.S. 42-6-102(17) |
| Connecticut | TLF | Conn. Gen. Stat. 38a-353 |
| Delaware | TLF | 21 Del. C. 2512 |
| District of Columbia (unverified) | 75% | D.C. Code 50-1331.01 |
| Florida | 80% | Fla. Stat. 319.30(3) |
| Georgia | TLF | O.C.G.A. 40-3-2 |
| Hawaii | TLF | Haw. Rev. Stat. 286-48 |
| Idaho | TLF | Idaho Code 49-123 |
| Illinois | TLF | 625 ILCS 5/3-117.1 |
| Indiana | 70% | Ind. Code 9-22-3-3 |
| Iowa | 70% | Iowa Code 321.52(4)(e) |
| Kansas | 75% | K.S.A. 8-197 |
| Kentucky | 75% | KRS 186A.520 |
| Louisiana | 75% | La. R.S. 32:702 |
| Maine | TLF | 29-A M.R.S. 602 |
| Maryland | 75% | Md. Code, Transp. 11-152 |
| Massachusetts | TLF | M.G.L. c. 90D, 1 |
| Michigan | 75% | MCL 257.217c |
| Minnesota | 80% | Minn. Stat. 168A.151 |
| Mississippi | TLF | Miss. Code 63-21-33 |
| Missouri | 80% | RSMo 301.010 |
| Montana | TLF | Mont. Code 61-3-211 |
| Nebraska | 75% | Neb. Rev. Stat. 60-171 |
| Nevada | 65% | NRS 487.790 |
| New Hampshire | 75% | RSA 261:22 |
| New Jersey | TLF | N.J.A.C. 13:21-22.3 |
| New Mexico | TLF | NMSA 66-1-4.16 |
| New York | 75% | 15 NYCRR 20.20 |
| North Carolina | 75% | N.C.G.S. 20-71.3 |
| North Dakota | 75% | N.D.C.C. 39-05-20.2 |
| Ohio | TLF | Ohio R.C. 4505.11 |
| Oklahoma | 70% | 47 O.S. 1111 (SB 1920, 2026) |
| Oregon | 80% | ORS 801.527 |
| Pennsylvania | TLF | 75 Pa.C.S. 102 |
| Rhode Island | 85% | R.I. Gen. Laws 27-9.1-4 (S 3115, 2026) |
| South Carolina | 75% | S.C. Code 56-19-480 |
| South Dakota | TLF | SDCL 32-3-51.19 |
| Tennessee | 75% | T.C.A. 55-3-211 |
| Texas | 100% | Tex. Transp. Code 501.091(15) |
| Utah | TLF | Utah Code 41-1a-1005 |
| Vermont | TLF | 23 V.S.A. 2001 |
| Virginia | 75% | Va. Code 46.2-1602.1 |
| Washington | TLF | RCW 46.04.514; WAC 284-30-320 |
| West Virginia | 75% | W. Va. Code 17A-4-10 |
| Wisconsin | 70% | Wis. Stat. 340.01(55g) |
| Wyoming | 75% | Wyo. Stat. 31-2-106 |
Some lines carry age limits. New York brands only vehicles 8 model years old or newer, Wisconsin only those under 7, and Minnesota only late-model or high-value cars. Nevada leaves paint, electronics and towing out of the repair figure; Texas leaves out repainting and sales tax.
How insurance companies run the total loss formula
The total loss formula is the cost of repairs plus salvage value compared with actual cash value. If the first two add up to the third or more, the car can be declared a total loss. It is the rule in all 21 TLF jurisdictions and the private test insurers run everywhere else.
Salvage value is what a salvage yard or auction buyer pays for the wreck. Published ranges disagree: one insurance site puts it at 10 to 30 percent of pre-accident value, another at 20 to 40 percent. Where they overlap, 20 to 30 percent, is the honest planning range, and the tool uses 25 percent when you leave the field blank. A newer model with good parts to strip sits at the high end.
ACV is market value, not what you paid and not the loan balance. Adjusters build it from comparables, recent sales of the same model, trim and mileage nearby, and then adjust for condition. Depreciation is why older vehicles total so easily: a $4,000 repair is a third of a $12,000 value but all of a $4,000 one.
One $9,000 estimate, three different answers
Take a sedan with a $12,000 actual cash value, a $9,000 repair estimate, no wreck value from the adjuster, and a $500 collision deductible. The damage ratio is 75 percent. At 25 percent, the wreck is worth $3,000.
- Florida (80 percent line): under the line, but $9,000 plus $3,000 equals the $12,000 value, so the formula says total. The tool shows “Likely a total loss on the insurer’s math.” Settlement: $12,000 minus $500, or $11,500.
- New York (75 percent): the estimate sits right on the line, so the branding rule is reached and a title brand follows on a car 8 model years old or newer.
- Texas (100 percent): far under the branding line, yet the same formula still favors a write-off.
Keep the car instead and the check is $11,500 minus the $3,000 wreck value, so $8,500, and you own a branded wreck. Have it fixed and the claim pays $8,500 toward the $9,000 bill while you cover the $500 deductible. Same cash either way, very different car at the end.
Is it better to have a car totaled or repaired? Signals that decide it
Neither outcome is better by default. Threads on the Car Talk community and Reddit argue it constantly, usually without the buyback math. If your car is totaled, the payout turns it into cash at today’s prices; a repair keeps a known car on the road. The cost to repair matters less than the value of the vehicle and what you owe on it. These are the signals we weigh first:
- Structural or airbag damage. Frame work and an airbag deployment raise costs and the odds of a supplement. When repair costs clear the formula by only a few hundred dollars, teardown usually finds the difference.
- Age and mileage. An older sedan past 100k miles with a big estimate is usually worth more as a payout than as a project, especially if other work is due. Sentimental value of the vehicle is real, but put a dollar figure on it before it decides the claim.
- Loan or lease balance. The payout goes to the lender first. If you owe more than ACV, gap coverage decides whether you walk away even; on a lease, the leasing company owns the car and makes the call.
- What a new car costs you. If replacing it means a loan at today’s rates, a sound repaired vehicle can be the cheaper way to keep driving than another car. Our repair or replace calculator runs that comparison month by month, and the guide to keeping an old car versus replacing it covers the longer view.
- Who did the repair math. A body shop estimate written before teardown is a floor, not a ceiling. Get a second written estimate from an independent shop; our guide on getting a repair estimate covers what to ask.
If you carry liability only, with no collision coverage, and the other driver is not at fault, no insurer pays for your car and the decision is a plain repair-versus-value call. Our guide to paying for body repair without insurance covers that case, our page on whether a car is worth fixing covers what happens when the cost of repair exceeds what the car is worth, and the auto body repair cost calculator prices the panels.
Keeping your totaled car: buyback math and the salvage title
Owner retention means you take the settlement minus salvage value and keep the vehicle. Insurers generally allow it, though a few title laws block it. If you want your car back, know the four costs that come with it.
- A salvage title. A buyback almost always produces one. In most of the country such a car cannot be registered or driven until it is repaired.
- An inspection to rebuild it. After the work, an inspection converts it to a rebuilt title, a permanent brand that insurers report to NMVTIS, the federal title database.
- Lower resale value. A rebuilt car typically sells for 20 to 40 percent less than the same car with a clean title, and lenders often avoid financing them.
- Thinner insurance coverage. Most insurers will write liability on a rebuilt car, but some limit or refuse collision and comprehensive.
Buying it back makes sense when the damage is mostly cosmetic, you can fix the car cheaply with aftermarket parts or a shop willing to repair the vehicle to that standard, and you plan to drive the car until it dies. It is a poor bet with structural damage or if you could sell within a few years, because the brand follows the car to every buyer.
Owe more than the car is worth? Gap insurance and diminished value
Gap insurance is optional coverage that pays the difference between the ACV payout and what you still owe on the loan or lease. The insurer pays the lender first, so without gap coverage a write-off can leave you making payments on a car that went to auction. Check your loan or lease paperwork before you argue for a total; some leases include gap.
Diminished value is the resale value a car loses after a crash and repair, even a good repair, because the accident shows up on vehicle history reports. When the other driver was at fault, many states allow a diminished value claim against that driver’s auto insurance; claims under your own policy are far more limited. Rules and amounts differ from place to place, so treat it as a question for the at-fault driver’s carrier, not a sum to count on.
Disputing the actual cash value in a total-loss settlement
Yes, you can ask for more money. The settlement is an offer, and the ACV is the number most worth checking. The page of the report we would read first is the comparables list, not the bottom line: one sale with the wrong trim level or far higher mileage pulls the car’s value down for everyone in the average.
- Ask the adjuster for the full valuation report, including each sale it used and its mileage.
- Check market value yourself with Kelley Blue Book and local listings for the same trim and options; book value is a starting point, not the final word.
- Send receipts for recent tires, brakes or major work that raised the condition rating.
- Ask whether sales tax, title and registration fees are included; some policies and local rules add them to the check.
Start with the estimator above: enter your state, the ACV, the estimate and your deductible, then compare its formula line with the settlement letter. If the math says repair and the insurer says total, ask for the salvage bid and valuation in writing. If you are still asking yourself, is it better to have a car totaled or repaired, let the payout, your loan balance and the title costs above settle it.
Questions owners ask about totaled cars
Can you ask for more money when your car is totaled?
Yes. Request the valuation report, challenge comparables that do not match your trim or mileage, and send records of recent work. A documented case is the only kind a claims handler can act on.
Can I keep my car if it is totaled?
Usually. The insurer pays the actual cash value minus your deductible and minus the salvage value, and the car comes back to you with a salvage title. A few jurisdictions restrict owner retention, so ask before you agree.
Can I drive a totaled car?
Not on a salvage title in most places. The car must be repaired and pass an inspection for a rebuilt title before it can be registered again and is treated as safe to drive.
How is salvage value determined?
Insurers base it on what a wreck like yours would bring at auction. Published ranges put it at roughly 20 to 30 percent of pre-accident value where two sources overlap, higher for newer cars with reusable parts.
Can you insure a totaled car after buying it back?
Once it carries a rebuilt title, most insurers will write liability coverage. Some limit or decline collision and comprehensive, so get a quote before you buy the car back.
Estimates only, not a quote or legal advice. Thresholds change; confirm yours with your DMV or insurance department before you sign a settlement. Last reviewed: October 2026.